
The Insurance Producers Guild
The Insurance Producers Guild is a strategic briefing for insurance professionals, focused on Medicare, ACA, life insurance, and the evolving insurance landscape. Each episode distills complex industry changes into clear, practical intelligence.
AI was used in the making of these podcasts.
The Insurance Producers Guild
EP24 How Much and Why ACA Marketplace Premiums Are Going Up in 2027
Use Left/Right to seek, Home/End to jump to start or end. Hold shift to jump forward or backward.
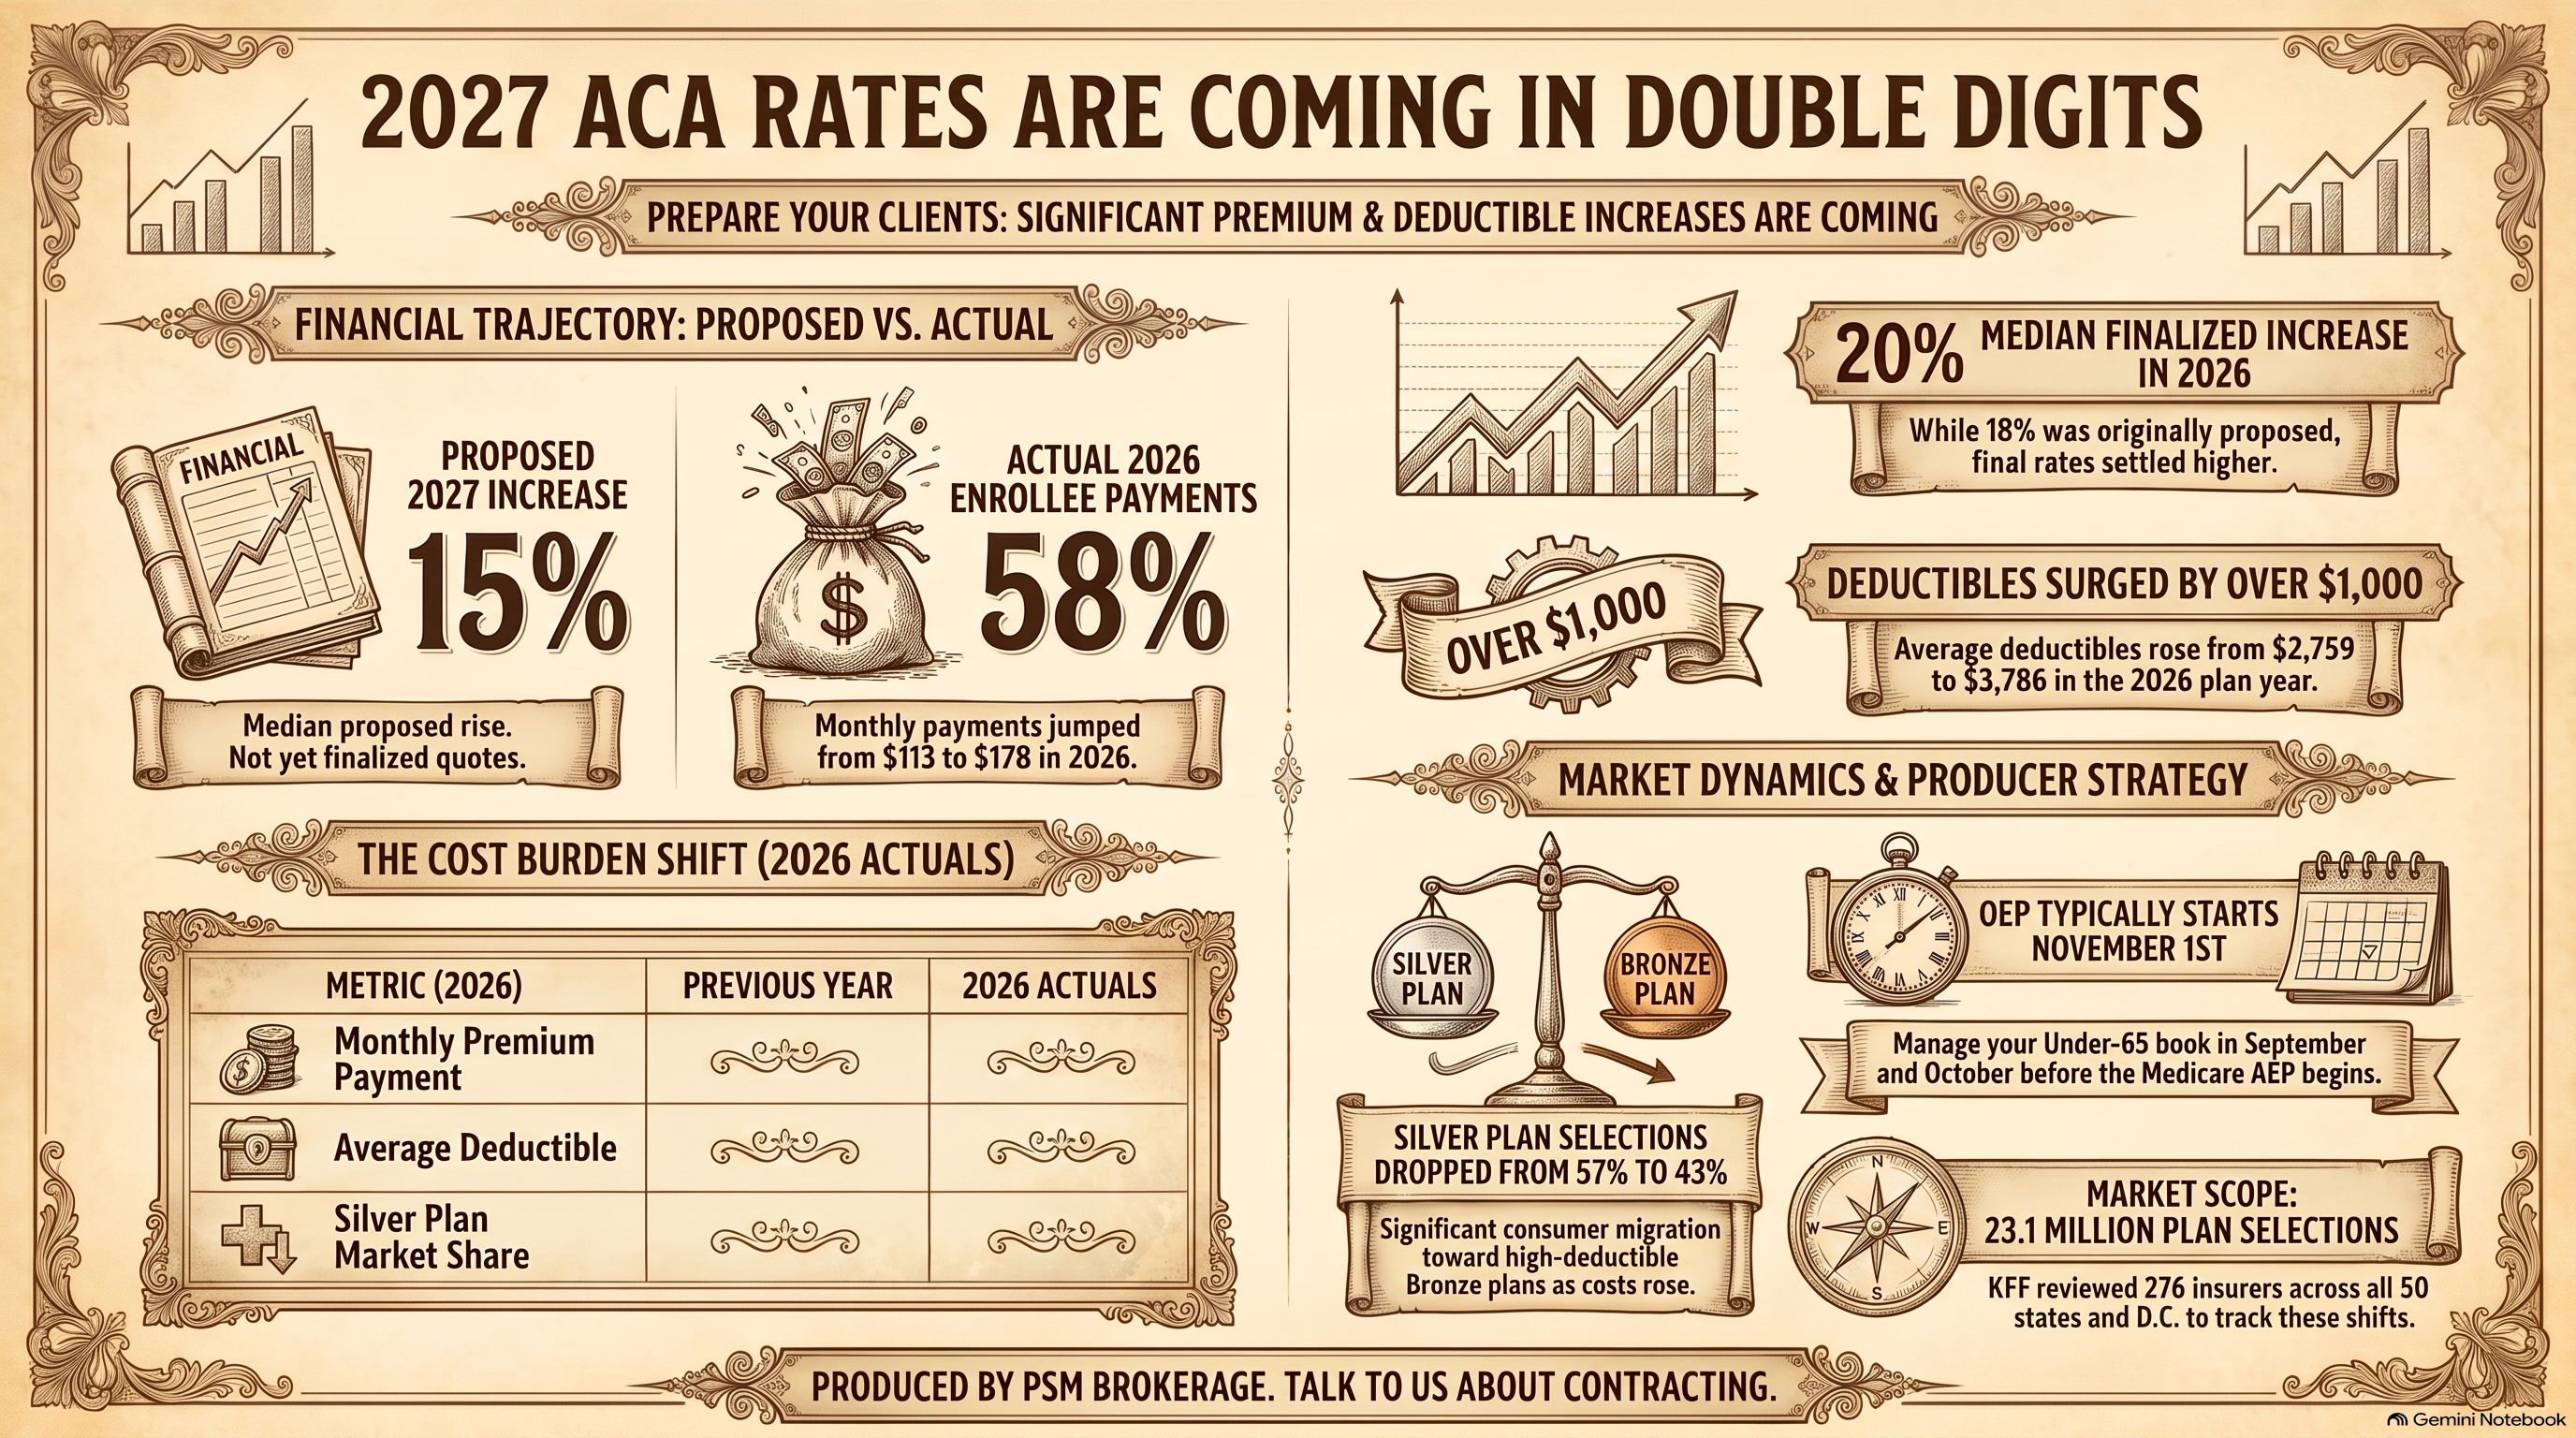
KFF’s August 3 analysis of 276 insurers found a median proposed 2027 ACA Marketplace premium increase of 15%, following a 20% median finalized increase for 2026. These rates are proposed and still require state approval.
Clients already absorbed major changes in 2026 after enhanced premium tax credits expired: average enrollee premium payments increased 58%, deductibles rose, and Silver enrollment declined. CMS reported 23.1 million Marketplace plan selections for 2026.
We break down what agents know now, what they should not quote yet, and how to book October reviews before November 1.
🔑 Key Topics Covered
- Proposed 2027 ACA rate increases
- 2026 client cost changes
- Marketplace enrollment shifts
- October review appointment strategy
🎯 What This Means for Agents
- Expect rate concerns before Open Enrollment
- Review subsidy and deductible changes early
- Avoid quoting unapproved 2027 premiums
- Prioritize vulnerable Marketplace clients now
🔗 Sources
KFF
2027 ACA Marketplace Premium Analysis
CMS
2026 Open Enrollment Report
📌 GO-DO: Build Your October Review List
Export your ACA, Marketplace, and under-65 clients this week. Prioritize clients who moved to Bronze in 2026 or lost enhanced-credit protection. Call each one without quoting a 2027 premium and book a 20-minute October review covering their plan, subsidy, and deductible.
Infographic: https://www.psmbrokerage.com/hubfs/The%20Insurance%20Producers%20Guild/IPG_EP24_Infographic.png
Slides: https://www.psmbrokerage.com/hubfs/The%20Insurance%20Producers%20Guild/IPG_EP24_Slides.pdf
The Insurance Producers Guild Podcast delivers intelligence for insurance agents looking to stay ahead of industry trends.
Follow the show and connect with PSM Brokerage to access tools, training, and support designed to help you grow your business.
Learn more: https://www.psmbrokerage.com
So um you are staring down the barrel of Medicare AEP, and your under 65 book is just sitting quietly in the corner.
SPEAKER_00Right. It is very tempting to just leave it right there.
SPEAKER_02Oh, absolutely. You know, you want to focus purely on seniors because, well, that feels like the immediate overwhelming priority.
SPEAKER_00It always does this time of year.
SPEAKER_02Yeah. But we really need to dissolve that fear right now because this is simply a scheduling reality. I mean, ACA open enrollment starts November 1.
SPEAKER_00Exactly. And ignoring the under 65 market right now is a mistake you just cannot afford to make.
SPEAKER_02Aaron Powell, no, you really cannot. So today we are bringing you a strategy session based on recent KFF and CMS data. We are going to map out exactly how the 2026 cost shock set the stage for 2027.
SPEAKER_00Aaron Powell I have been through this before in past cycles. You know, the 2026 cost shock already happened and it fundamentally altered your client's wallet.
SPEAKER_02It really did.
SPEAKER_00Yeah. And now the 2027 proposed rates are signaling that the turbulence is, well, it is far from over.
SPEAKER_02For sure. And our mission today is to give you the exact playbook, including a very specific script, to protect your book of business right now.
SPEAKER_00You need that playbook before November hits.
SPEAKER_02Completely. So um we have to understand the mechanics of this turbulence before we can monetize it. Let us look at the August 2026 KFF report.
SPEAKER_00That is a crucial piece of data.
SPEAKER_02It is. This analysis covers 276 insurers across all 50 states and the District of Columbia. And the median proposed premium increase for 2027 is 15%.
SPEAKER_00Wow. 15%.
SPEAKER_02Yeah. It is not just a localized issue happening in one or two states, it is a national correction.
SPEAKER_00And this marks the second consecutive year of double-digit requests. We saw a very similar scenario play out last year.
SPEAKER_02Right, I remember that.
SPEAKER_00Yeah. Carriers proposed an 18% increase last year, and the finalized rate actually landed at 20%. So the pattern is establishing itself clearly.
SPEAKER_02It really is.
SPEAKER_00And while 15% is slightly lower than last year's request, KFF notes it is still the second highest requested rate change since 2018.
SPEAKER_02That is huge. And you know, when you see a 15% proposed hike, the immediate reaction is frustration. Clients will see the headlines and panic. But as an agent, you cannot just shrug and blame the carriers. You have to explain the actual market mechanisms driving those numbers.
SPEAKER_00Exactly. We are not here to criticize our carrier partners. Rising medical prices are just a fundamental market reality.
SPEAKER_02Yeah, but that is only half the story, right?
SPEAKER_00Aaron Powell It is. The other half is the expiration of the enhanced premium tax credits that ended in 2025.
SPEAKER_02Aaron Powell Oh, right. Those credits were massive.
SPEAKER_00They really were. They acted as a massive financial shield for consumers. They masked the true underlying cost of healthcare inflation.
SPEAKER_02Aaron Powell So people did not feel the pinch.
SPEAKER_00Exactly. But when that shield vanished, well, the market had to absorb the reality of those costs.
SPEAKER_02So let us break down the psychology of what happens when that shield disappears. Because a client gets their renewal notice, right? Yes. And they see their out-of-pocket monthly cost is going up significantly. It is human nature to react offensively.
SPEAKER_00100%.
SPEAKER_02Like if I feel completely healthy and my insurance premium spikes, I might decide to roll the dice. I might drop my coverage entirely, or, you know, by the absolute bare minimum plan just to have something on paper.
SPEAKER_00You are describing the exact mechanism of adverse selection.
SPEAKER_02Right.
SPEAKER_00When prices go up out of pocket, the healthiest individuals are often the first to exit the comprehensive risk pool.
SPEAKER_02Aaron Powell Because they do not think they need it.
SPEAKER_00Precisely. They simply do not feel they need the coverage urgently enough to justify the new price tag.
SPEAKER_02Aaron Powell, which leaves the insurance carrier with a pool of people who are, well, actively using their benefits.
SPEAKER_00Yes. People managing chronic conditions or planning for surgeries, they are not dropping their coverage no matter what the premium does.
SPEAKER_02They cannot afford to.
SPEAKER_00Exactly. Which means the overall morbidity of the risk pool increases. The pool becomes sicker on average.
SPEAKER_02Right.
SPEAKER_00So carriers then have to adjust their 2027 rates to cover that increased cost of care. It is a mathematical necessity to keep the plan solvent.
SPEAKER_02So this brings us to a massive opportunity for the agent because you have to act as the expert navigator here.
SPEAKER_00You really do.
SPEAKER_02When a client calls you in a panic about a 15% headline, they're basically ignoring the check engine light on their dashboard.
SPEAKER_00That is a great way to put it.
SPEAKER_02You know, they know something is wrong. They are afraid of what the mechanic will charge them, and they need you to diagnose the actual problem. So how are you handling that initial phone call?
SPEAKER_00Well, I operate on a hard rule for this exact scenario.
SPEAKER_02Okay, what is the rule?
SPEAKER_00Proposed rates are not quoted rates.
SPEAKER_02Ah, I love that.
SPEAKER_00You do not put a 2027 dollar amount on a kitchen table until the state approved rates are officially public.
SPEAKER_02Because you could be quoting a 15% increase based on a headline, and the state might approve 10%.
SPEAKER_00Right. Or as we saw last year, they might approve 20%.
SPEAKER_02Yeah, and if you quote the wrong number, you look like you do not know your own industry.
SPEAKER_00Exactly. You protect your credibility by dealing only in finalized facts. You acknowledge the trend with the client, and you validate their concern about the headlines, but you refuse to quote a phantom number.
SPEAKER_02That restraint is really powerful.
SPEAKER_00It builds trust.
SPEAKER_02It definitely does. And um, if everyone is fleeing to cheaper plans to escape the monthly premium, agents must be looking at a book of business that is essentially a ticking time bomb of unpayable deductibles.
SPEAKER_00It absolutely is a time bomb.
SPEAKER_02We have to connect these 2027 proposals to the immediate past. A 15% proposed hike matters so much right this minute because your clients are still bruised from the financial hits they took in 2026.
SPEAKER_00Oh, they are very bruised. And that bruising is heavily documented in the KFF May 2026 data.
SPEAKER_02Right. Let us get into that data.
SPEAKER_00We saw a dual shock caused by the expiration of those enhanced credits. Enrolly monthly payments jumped 58%.
SPEAKER_02Wait, 58%?
SPEAKER_00Yes. The average enrollee went from paying $113 a month to $178 a month.
SPEAKER_02We really have to pause on that number. A jump of $65 a month is nearly $800 a year out of a family budget.
SPEAKER_00It is a lot of money.
SPEAKER_02For households already balancing inflation at the grocery store, that is a massive blow. They cannot just absorb that quietly. They react.
SPEAKER_00Yeah, they react by squeezing the budget wherever they can.
SPEAKER_02It is exactly like squeezing a water balloon, you know. Clients tried to avoid that 58% premium spike by squeezing the balloon. They tightened their belts and looked for cheaper monthly plans.
SPEAKER_00But the water has to go somewhere.
SPEAKER_02Exactly. The financial pressure did not disappear. The cost simply popped out on the deductible side. According to the data, the average deductible grew 37%.
SPEAKER_00Which is staggering. We are talking about a jump of more than $1,000 per person. Wow. The average deductible reached $3,786 in 2026. That financial pressure completely changed the shape of your book of business.
SPEAKER_02The CMS March 2026 data illustrates this perfectly, right?
SPEAKER_00It really does.
SPEAKER_02Silver plan signups fell from 57% down to a record low 43%.
SPEAKER_00Huge drop.
SPEAKER_02And at the exact same time, bronze plans surged to capture 40% of the market. Gold plans just sat at 17%. Right. So compared to the 2025 open enrollment period, bronze enrollment rose 10 percentage points, while silver fell nearly 14 points.
SPEAKER_00Because people were scrambling for a lower monthly payment, even if it meant taking on substantially more risk.
SPEAKER_02They were just desperate for relief.
SPEAKER_00They were. And what we need to analyze closely is the behavior of the people who were hovering just above the subsidy cliff.
SPEAKER_02Okay, yes.
SPEAKER_00I am talking about clients sitting at 400 to 500% of the federal poverty level.
SPEAKER_02So let us explain the math behind that cliff for a second. Historically, if a family made even one dollar over that 400% federal poverty level mark, they fell off a cliff in terms of government assistance.
SPEAKER_00Right. It was a hard stop.
SPEAKER_02But the enhanced credits we had prior to 2026 acted as a bridge over that cliff. They kept premiums capped at a percentage of income.
SPEAKER_00Exactly. And when those enhanced credits expired, that specific group lost their pricing shield entirely.
SPEAKER_02They were just left exposed.
SPEAKER_00Completely. Yeah. And even though they only represented about 3% of the 2025 plan selections, they counted for a disproportionately massive share of the drop in signups.
SPEAKER_02Wait, really? How massive?
SPEAKER_00A staggering 27% of the total drop in signups came from this specific narrow income bracket.
SPEAKER_02Oh wow. That is a huge concentration.
SPEAKER_00It is. Many of your clients in that group simply bought down to a higher deductible bronze plan rather than absorb the full silver price increase.
SPEAKER_02Because they had no other choice.
SPEAKER_00Right. They could not make the kitchen table math work any other way.
SPEAKER_02Which means the composition of an agent's book is now fundamentally different. The exchange coverage remains near a record high, though. The CMS data shows 23.1 million consumers selected or were automatically re-enrolled in coverage for 2026.
SPEAKER_00Aaron Powell It is a massive market. And that 23.1 million number holds strong even after CMS reported they ended advanced payment of the premium tax credit or coverage for nearly 1.5 million people. Aaron Powell Right.
SPEAKER_02The people found ineligible for financial assistance or enrolled without authorization.
SPEAKER_00Exactly. So the overall pool is still huge.
SPEAKER_02The overall pool is huge, yes, but it is heavily bronze. It is highly deductible heavy.
SPEAKER_00Very much so.
SPEAKER_02Your clients are carrying far more financial risk today than they were two years ago. They are walking around with deductibles approaching $4,000.
SPEAKER_00Which is terrifying for most families.
SPEAKER_02It is. If they break an arm or, you know, if they need an unexpected scam, they are entirely exposed before their insurance actually helps them.
SPEAKER_00This is exactly why waiting until November to talk to them is a strategic failure.
SPEAKER_02A complete failure.
SPEAKER_00The patterns from past cycles tell us that early intervention is the only way to retain these clients. If you wait for them to open their renewal letter, you are reacting instead of leading.
SPEAKER_02Because hope is not a strategy.
SPEAKER_00Definitely not.
SPEAKER_02Waiting until October 15th when you are completely buried in Medicare AEP means you are already late for the under 65 market. We must monetize this pattern today. Right, today. We need to control the narrative before the open enrollment period officially begins.
SPEAKER_00You have to position yourself as the protector of their finances before the panic sets in.
SPEAKER_02So here is the concrete selling technique. This is what I would say word for word to clients this week. Grab a pen and write this down. You call them up and say, open enrollment for your marketplace plan starts November 1. 2026 already changed what a lot of people pay. 2027 rates are being filed in the double digits. I will not quote a number I do not have. I want 20 minutes in October to review your current plan, your subsidy, and your deductible before November 1.
SPEAKER_00That script is highly effective because it builds urgency without causing a panic attack.
SPEAKER_02Yes, exactly. It is calm but urgent.
SPEAKER_00And it respects the rule we established about phantom numbers. You are acknowledging the double-digit filings loudly and clearly, but you are not promising a specific rate.
SPEAKER_02Because we do not have one.
SPEAKER_00Right. It puts the agent firmly in the driver's seat.
SPEAKER_02It does. The client instantly realizes you are watching the market on their behalf. You are the professional tracking the data while they are busy living their lives.
SPEAKER_00They feel taken care of.
SPEAKER_02So how does an agent operationalize the script today?
SPEAKER_00Well, you need to execute specific steps immediately. Go into your CRM this afternoon, pull every single ACA and under 65 client file.
SPEAKER_02Every single one.
SPEAKER_00Every one. You need to systematically tag your bronze buy-downs. Find every client who downgraded to a bronze plan last year to save a buck. Put a massive red flag on their file.
SPEAKER_01Because they are the ones sitting on that $3,786 deductible time bomb.
SPEAKER_00Exactly. You also need to tag anyone sitting near that 400% federal poverty level mark.
SPEAKER_02The people hovering over the cliff.
SPEAKER_00Yes. Those specific clients are your most vulnerable, high priority reviews. They are the ones who felt the 2026 cost shock the hardest. And they are the ones who will need the absolute most guidance navigating the 2027 rates.
SPEAKER_02Okay, so to make this process seamless, you need the right structural backing. Because you cannot do this all manually while also prepping for Medicare.
SPEAKER_00No, you would drive yourself crazy.
SPEAKER_02This is where verified PSM brokerage services come in to do the heavy lifting for you.
SPEAKER_00You have to be ready to write the business without administrative delays.
SPEAKER_02Right. First, you need to use PSM contracting support. Ensure all your marketplace appointments are locked in and active.
SPEAKER_00You cannot afford to have a minor contracting issue slow you down when November hits and the floodgates open.
SPEAKER_02That is foundational. If you cannot write the business, none of this matters.
SPEAKER_00Right.
SPEAKER_02Second, head over to the marketing hub. You can access a co-branded review letter there that mirrors the script we just discussed.
SPEAKER_00Oh, that is perfect.
SPEAKER_02Yeah. And the compliance and legal department can clear that letter for immediate deployment to your book of business. You do not have to invent the wheel from scratch. You just have to use the verified tools provided to you.
SPEAKER_00Aaron Powell Having that marketing cleared and ready before the AEP wave completely takes over your schedule is critical.
SPEAKER_02You need that peace of mind.
SPEAKER_00Get the compliance box checked right now so you can focus entirely on having those valuable client conversations in October.
SPEAKER_02So we are laying out a very clear path here. The data shows a market under pressure.
SPEAKER_00A lot of pressure.
SPEAKER_02The clients are squeezed between rising premiums and exploding deductibles. The agent who steps in as the expert guide wins the retention battle.
SPEAKER_00And if we pull back and look at the bigger picture, this shift in the market opens up a massive cross-selling opportunity.
SPEAKER_02Oh, definitely. Tell me more about that.
SPEAKER_00Well, with clients now sitting on average deductibles of $3,786, the ACA book is no longer just a standalone health insurance conversation.
SPEAKER_02Because they have a huge gap in coverage.
SPEAKER_00Right. You cannot just sell them a high deductible plan and walk away.
SPEAKER_02No, that is doing them a disservice.
SPEAKER_00Exactly. It is the perfect gateway to discuss ancillary products.
SPEAKER_01Ah, right. Like what?
SPEAKER_00Hospital indemnity plans, accident coverage, and critical illness policies. These can shield them from those exact out-of-pocket gaps.
SPEAKER_02That makes total sense.
SPEAKER_00You are not just selling them a premium anymore. You are building a wall to protect them from a massive deductible.
SPEAKER_02That is incredibly valuable for the client and the agent. That's this episode of the Insurance Producers Guild. Stay tuned for the next one. If you're not already with PSM Brokerage, this is the intelligence our agents get. Talk to us about contracting.